Welcome! Where would you like to log in?

Sign up and get
PRO free for 14 days
Once your PRO trial is over you can continue using Landlord Studio GO completely free.
By continuing you agree to our Terms & Conditions.

Visiting from the
United Kingdom?
Please visit our United Kingdom site for a better experience
Continue
Passive Activity and Passive Activity Loss Limitations in Real Estate
Learn how passive activity loss limitations restrict rental deductions, plus exceptions like the $25K allowance and real estate professional rules.

Read summarized version with:


If you actively manage your rental properties, you may be wondering whether your real estate income qualifies as active or passive under IRS rules. The distinction is crucial because it determines how much of your rental property losses you can deduct against other income.
Generally, rental income is considered passive, even if you self-manage your properties using a property management software like Landlord Studio. This classification subjects rental losses to passive activity loss limitations. However, if you qualify as a real estate professional, you may be able to deduct rental losses against your ordinary income, potentially lowering your tax burden significantly.
In this guide, we’ll break down:
- Passive activity loss limitations and how they impact your rental property deductions
- The IRS definition of a real estate professional
- How to determine material participation in rental activities
- What is a passive loss?
- How software can help you maximize your deductions

What Are Passive Activity Loss Limitations?
Essentially, because the IRS classifies rental income as passive, any losses from your rental properties generally cannot be used to offset non-passive income, such as wages or business profits. These restrictions are known as Passive Activity Loss (PAL) limitations, established under Section 469 of the IRS Code.
However, there are exceptions:
Limited deduction for lower-income landlords – If your modified adjusted gross income (MAGI) is under $100,000, you may deduct up to $25,000 of rental real estate losses so long as you actively participate in the rental activity.
Real Estate Professional Exception – If you meet IRS criteria as a real estate professional, your rental losses are considered active and can be deducted against your ordinary income.
We go into greater detail below — Click here to skip ahead.
Determining Your Real Estate Professional Status
The IRS allows those who are deemed to be “real estate professionals” to take more or less unlimited deductions against their income – and not just their real estate income. However, qualifying as a real estate professional isn’t as easy as having or managing a few rental properties.
Rather, to qualify as a “real estate professional”, you must spend at least 750 hours in a real estate trade or business, and more than half your total working hours must be in a real estate trade or business. This essentially means that if you have a day job that isn’t in real estate, then you are going to have a hard time qualifying as a “real estate professional”.
This is the underlying rule; however, as with most things where the IRS is involved, it’s not that simple. Along with the above, you must materially participate in your rental activity.
According to IRS Topic No. 425, “material participation” is involvement in the operation of a trade or business activity on a “regular, continuous, and substantial basis.” Meaning, even if you’re a real estate professional by day, if you own rentals but have a property manager, you won’t qualify.
Tests For Qualifying As Materially Participant In Rental Activity
- You actively participated in the management of your properties for more than 500 hours.
- Your participation constituted the majority of all individuals' involvement in the activity for the tax year, even those who had no ownership interest.
- You participated in the activity for more than 100 hours during the tax year, equal to or exceeding the participation of any other individual, regardless of ownership interest.
- The activity is considered a significant participation activity, and you participated in all significant participation activities for more than 500 hours. A significant participation activity refers to a trade or business activity in which you spent over 100 hours during the year, without meeting the material participation tests, except for this particular test.
- You materially participated in the activity (excluding meeting the fifth test) for a minimum of five tax years out of the last ten, whether consecutive or not.
- The activity falls under the category of a personal service activity, and you materially participated for at least three preceding tax years. Personal service activities include fields like health, law, engineering, architecture, accounting, actuarial science, performing arts, consulting, or any other trade or business where capital isn't a significant factor in generating income.
- Considering all relevant circumstances, you participated in the activity consistently, continuously, and significantly throughout the tax year.
If one spouse meets the 750-hour test, both spouses can combine their time spent on rental properties for material participation purposes. Consequently, losses can be offset against the income of either spouse. This strategy is particularly advantageous for couples in which one spouse is involved in a real estate trade or business, works part-time, or is primarily engaged in investment activities rather than other employment.
In any year you elect to be treated as a “real estate professional” for tax purposes, you’ll need to keep a log of all hours worked within a real estate trade or business. It is also prudent to keep a log of hours spent in non-real estate trades or businesses, if applicable, to ensure you’re spending more than half your total working time in a real estate trade or business.
Related: 6 Real Estate Investing Tax Strategies You Need To Know
Passive Activity Losses If You Don’t Qualify as a “Real Estate Professional”
If you don’t qualify for the Real Estate Professional Status, don’t worry, all is not lost. As long as you partake in the management of your properties, you can still access the benefits of the sizeable tax advantages available for real estate investors, such as:
- Depreciation and accelerated depreciation on your rental properties
- Mortgage interest
- Property taxes
- Insurance and maintenance costs
- Mileage and travel expenses related to property management
- Deferred capital gains through 1031 exchanges
Tracking and categorizing expenses efficiently can help maximize deductions. Landlord Studio offers automated expense tracking, ensuring you don’t miss out on tax-saving opportunities.
About Passive Activity Loss Limitations
The Passive Activity Loss (PAL) limitations are tax rules that restrict taxpayers from using losses from passive activities to offset non-passive income. These rules were established under the Tax Reform Act of 1986 to prevent taxpayers from using passive losses to reduce their taxable income from active sources (such as W2 wages or other business income).
Rental real estate is generally considered passive unless the taxpayer qualifies as a real estate professional. However, if you don’t qualify for the Real Estate Professional Status, you can still deduct up to $25,000 of your rental losses from your ordinary income as long as you are actively participant.
Here’s how it works:
- If your modified adjusted gross income (MAGI) is $100,000 or less, you can deduct up to $25,000 of passive losses against your passive income.
- If your MAGI exceeds $100,000, your deduction decreases by $1 for every $2 of income above this threshold.
- Once your MAGI reaches $150,000, you cannot deduct any passive losses against ordinary income.
These limits apply to both individuals filing as single or married filing jointly.
In order to claim losses against your ordinary income, you must demonstrate active participation in the activity. Active participation entails having a role in making management decisions for the business. This requirement is less stringent than the material participation criteria applicable to real estate professionals, which is discussed separately below.
Passive Loss Limitations Example
For instance, if your MAGI is $100,000 and your rental properties generate a net loss of $30,000, you can deduct $25,000 of this loss against your ordinary income as long as you materially participate in the rental activities. The remaining $5,000 will be carried forward to future years.
However, if your MAGI is $125,000, the deductible amount of the loss is reduced to $12,500. Each dollar over $100,000 reduces the deduction by $0.50. If your MAGI exceeds $150,000, you cannot deduct any of these losses against your ordinary income, and the entire $30,000 loss is carried forward to be used in future years.

What Is A Passive Loss?
A passive loss is any financial loss incurred with an investment in a trade or business enterprise where the investor is not materially participant. However, as stated above, the IRS deems real estate, even if the investor is materially participant as passive.
Passive losses can come from a number of activities, such as the following:
- Rental real estate (though there are some exceptions eg. if you qualify as a “real estate professional”)
- Leasing of equipment
- Partnerships, S-Corporations, and limited liability companies in which the taxpayer has no material participation.
If you are unsure whether a loss should be classified as passive or not, it is advisable to consult with a professional accountant to ensure your taxes are being filed correctly.
Most landlords don’t qualify as real estate professionals. As such, it’s important for them to understand the relevant passive activity loss limitations. Everyone’s situation is different, and if you think any of the above applies to you it’s recommended that you consult with your CPA or a licensed tax professional.
Landlord Tip: If you have a full time W2 job and try to claim Real Estate Professional Status you will likely open yourself up to an IRS audit as the IRS knows it would be incredibly hard for you to meet the materially participant requirements outlined above.
Passive Activity Loss Limitations: Final Thoughts
Understanding the difference between passive and active real estate income is essential for maximizing tax benefits. If you qualify as a real estate professional, you can unlock significant tax deductions. Otherwise, be mindful of passive loss limitations and consider strategies like spouse participation or strategic expense tracking.
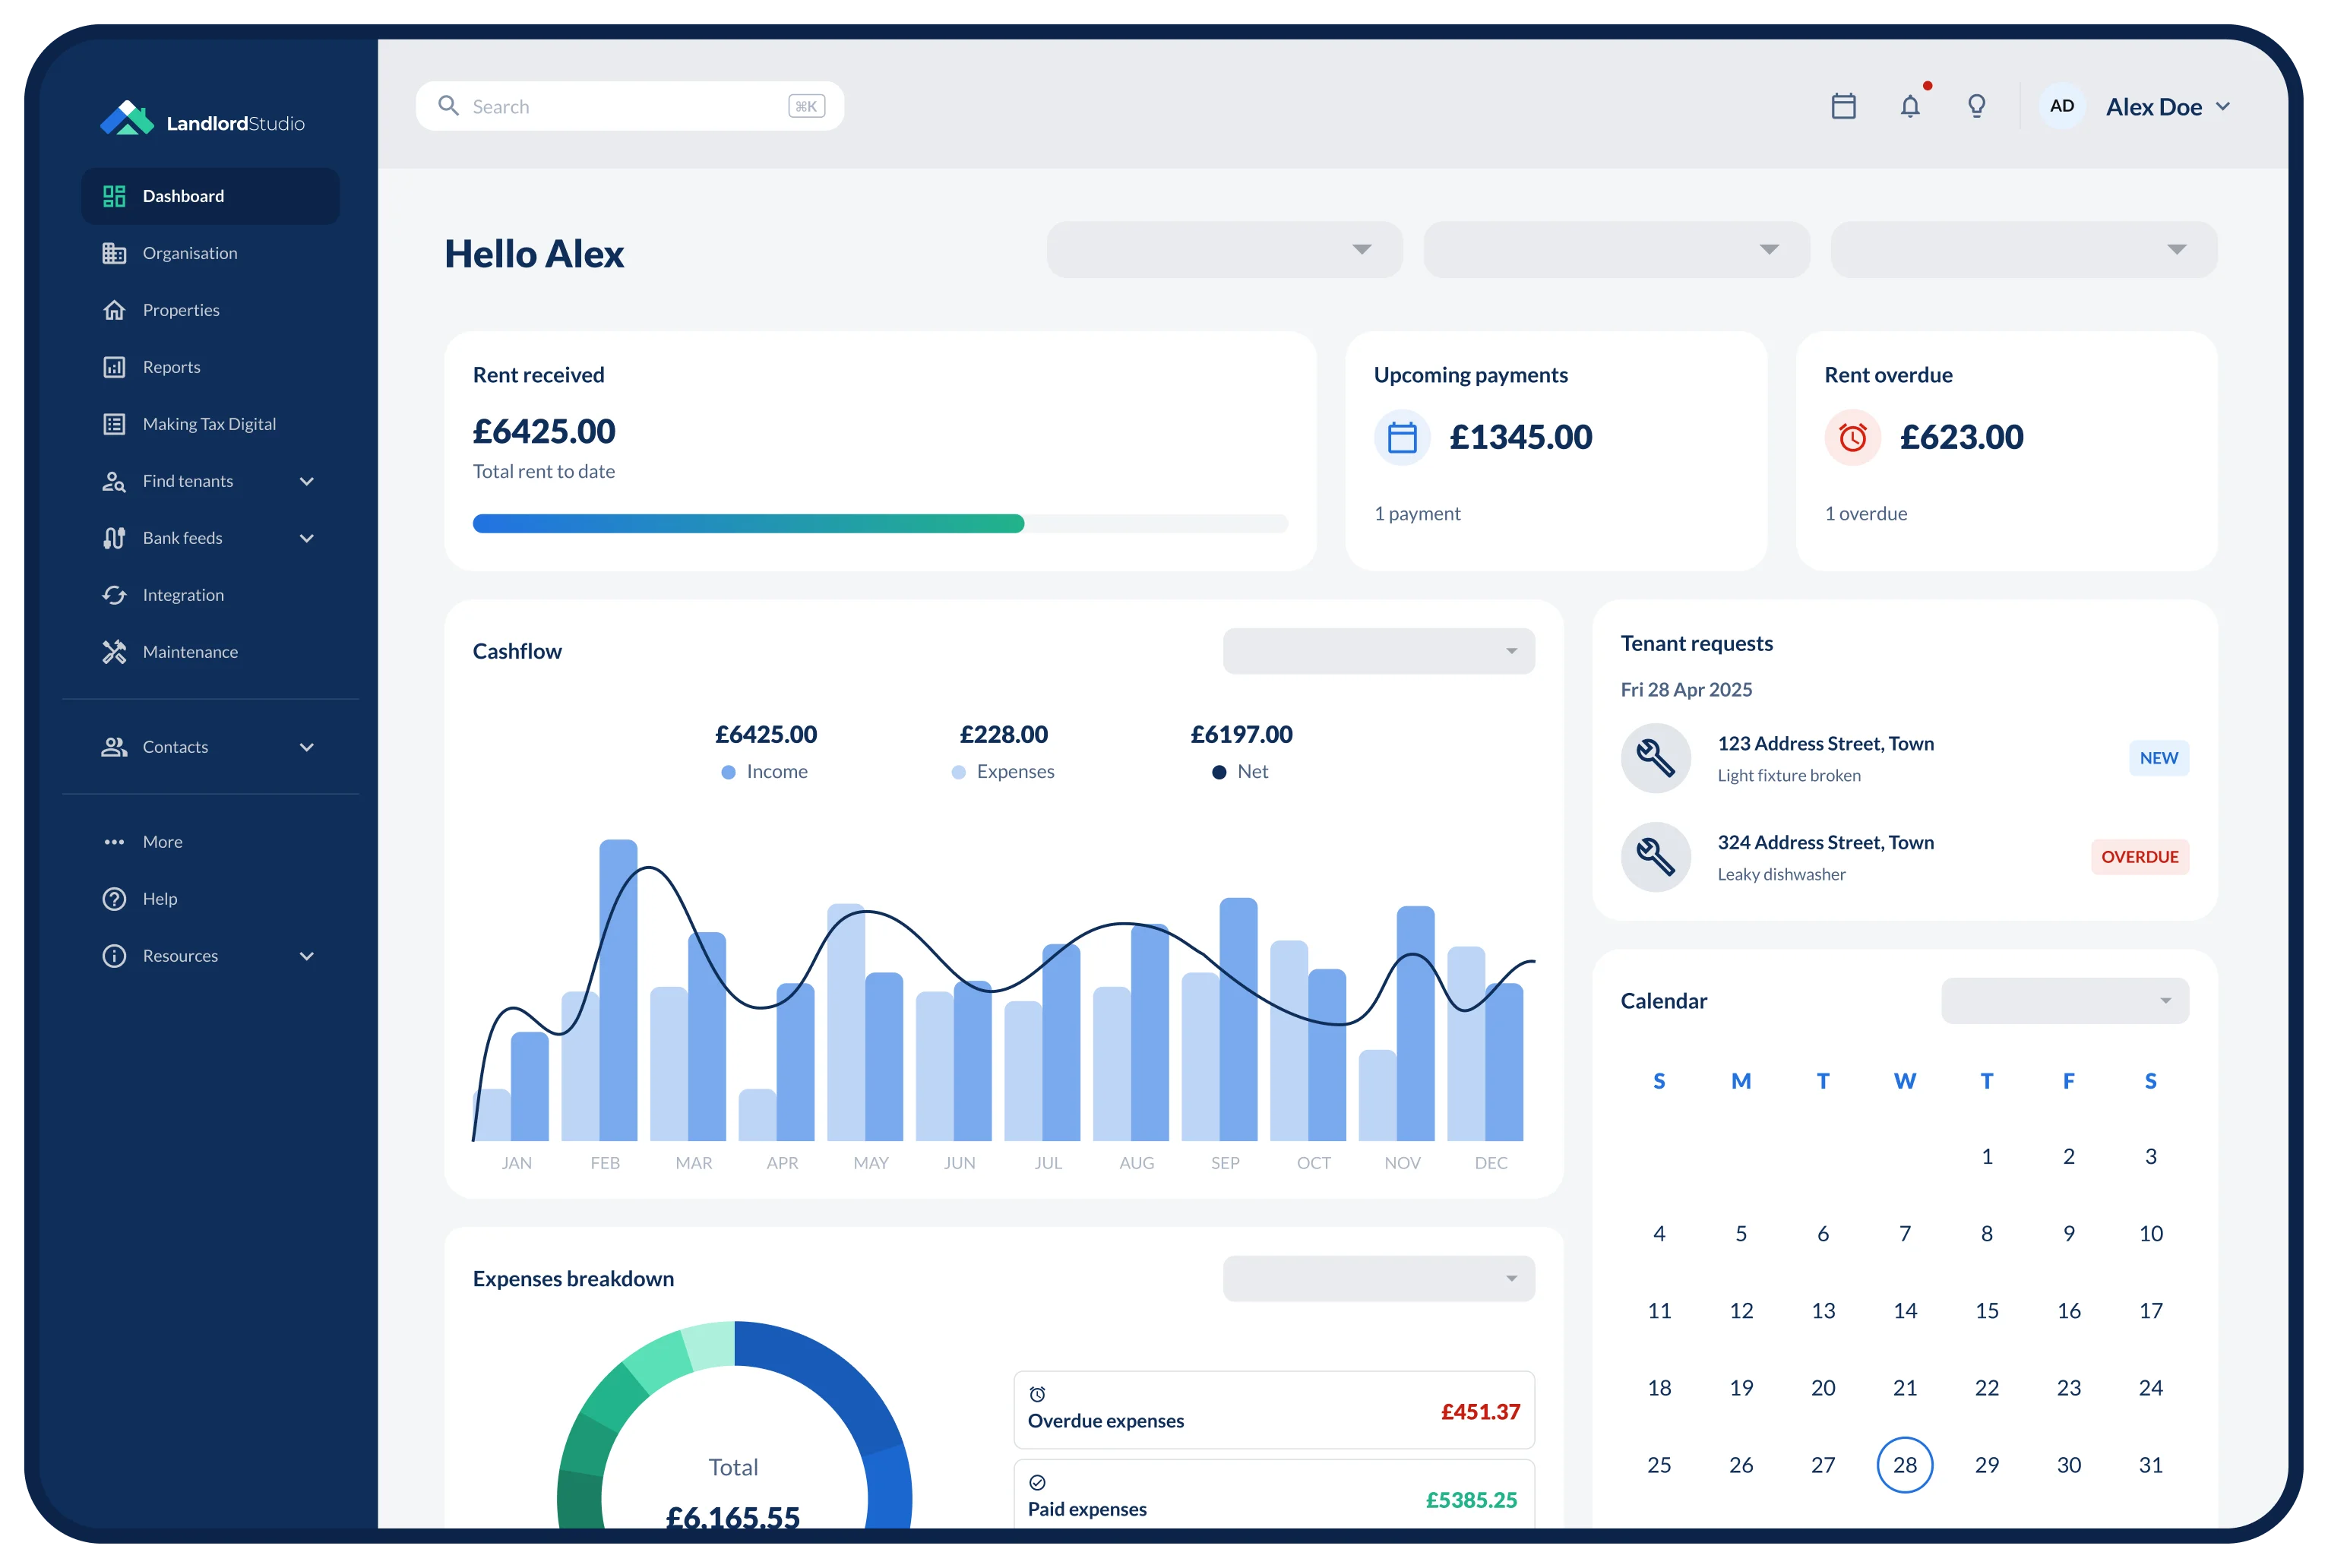
To simplify rental income tracking and tax preparation, consider using Landlord Studio—a powerful tool that helps landlords maximize deductions and stay IRS-compliant.
Create your free Landlord Studio account today to find and screen tenants, collect rent online, and streamline your rental property accounting for a more profitable rental portfolio.
You Might Also Like
- A Landlords Guide to Tax on Rental Income
- A Breakdown of your Schedule E Expense Categories
- How to Qualify as a Real Estate Professional
- 7 Tax Saving Strategies for Property Investors
- Top 7 IRS Audit Triggers Real Estate Investors Need to Know
FAQs: Passive Activity Loss Rules & Real Estate Tax Benefits
What is the limitation on passive activity losses?
Passive activity losses can only be deducted against passive income. If your MAGI is below $100,000, you can deduct up to $25,000 in passive losses against your ordinary income. The deduction phases out between $100,000 - $150,000.
What is the loophole for passive activity loss?
The main loophole is qualifying as a real estate professional under IRS rules. If you meet the 750-hour rule and materially participate in your rentals, your losses are considered active and deductible against all income.
What is the passive activity loss limitation under Section 469?
Section 469 of the IRS Code classifies rental activities as passive, restricting the use of rental losses to offset non-passive income unless you qualify as a real estate professional.
What are the IRS passive loss rules?
Passive losses can only offset passive income unless you meet an exception, such as Real Estate Professional Status. Unused losses can be carried forward to future years.
What are the three loss limitations?
- Basis Limitation: You can only deduct losses up to your investment basis in the property.
- At-Risk Limitation: Losses are limited to the amount you have at risk (e.g., loans you are personally liable for).
- Passive Activity Loss Limitation: Passive losses can only offset passive income, unless you qualify as a real estate professional.


About Landlord Studio

Landlord Studio is an easy to use property management and accounting software designed for landlords.
Find and screen tenants, collect rent online, track income and expenses, run reports, and more - all for free.
Create your FREE account with Landlord Studio today.

From finding tenants to filing taxes. Reduce vacancies and maximize your portfolio ROI with software designed for you.
Get started for free