Buy-to-let (BTL) refers to the practice of purchasing a property with the specific intention of renting it out to tenants rather than using it as a primary residence. This type of investment strategy is popular in the UK as it allows investors to generate regular rental income while potentially benefiting from capital growth as property values rise. A buy-to-let property can be residential or commercial, but in most cases, it refers to residential real estate.
Overview of Buy-to-Let Investments
The fundamental concept of buy-to-let is simple: an investor purchases a property and rents it out to tenants. The investor becomes a landlord and is responsible for maintaining the property, ensuring that it complies with legal standards, and managing the relationship with tenants. The goal of most buy-to-let investors is twofold:
- Rental Income: The primary objective is to generate monthly rental income, which can provide a steady and predictable cash flow. Ideally, the rent charged will exceed the costs of owning the property, such as mortgage repayments, maintenance, insurance, and other expenses, resulting in a net positive return each month.
- Capital Growth: Over time, property values in the UK have generally increased, meaning buy-to-let investors can also benefit from long-term capital appreciation when they eventually sell the property. However, capital growth is never guaranteed, and property values can fluctuate based on market conditions.
Buy-to-Let Mortgages
For those who require financing to purchase a buy-to-let property, a standard residential mortgage won't suffice. Instead, they will need to apply for a buy-to-let mortgage. Buy-to-let mortgages differ from regular residential mortgages in several ways:
- Higher Interest Rates: Buy-to-let mortgages typically have higher interest rates than residential mortgages because lenders view these loans as riskier. There is always the possibility that tenants may default on rent or the property could remain vacant, impacting the landlord's ability to keep up with mortgage payments.
- Larger Deposit Requirements: Lenders usually require a larger deposit for buy-to-let properties—typically around 25% to 40% of the property's value. This ensures that the borrower has substantial equity in the property and mitigates the lender's risk.
- Affordability Assessment: Instead of assessing the borrower’s personal income, lenders primarily focus on the expected rental income of the property to determine affordability. As a rule of thumb, the rental income should be at least 125% to 145% of the monthly mortgage repayments, allowing for a buffer in case of interest rate increases or unexpected costs.
Related: Bridge-To-Let Loans: A Guide to Financing Your Next Investment Property
Types of Buy-to-Let Investments
Buy-to-let investments come in different forms, and landlords can choose properties based on their strategy and target tenants:
- Residential Buy-to-Let: The most common form of buy-to-let, this involves purchasing a residential property to rent out to individuals, couples, or families. These properties can be single-family homes, apartments, or flats.
- Houses in Multiple Occupation (HMO): An HMO is a property rented out to multiple tenants who are not part of the same household. Each tenant rents a room or portion of the property while sharing common facilities such as the kitchen or bathroom. HMOs can offer higher rental yields but are subject to stricter licensing and regulation.
- Student Accommodation: Investing in properties specifically targeted at students can provide a reliable stream of income, particularly in cities with large universities. However, these properties may require more frequent maintenance due to the high turnover of tenants.
- Commercial Buy-to-Let: Some investors opt to purchase commercial properties such as office spaces, retail units, or industrial buildings to lease out to businesses. This type of buy-to-let investment typically requires a larger initial capital outlay and is subject to different laws and taxes.
Tax Considerations for Buy-to-Let Investors
Buy-to-let investments come with several tax implications, and investors need to understand these to maximize their returns.
- Rental Income Tax: Rental income is considered taxable income, and landlords must declare this on their annual tax returns. Depending on their total income, landlords may be taxed at the basic rate (20%), higher rate (40%), or additional rate (45%).
- Stamp Duty Land Tax (SDLT): Buy-to-let investors must pay a 3% surcharge on top of the standard stamp duty rates when purchasing a property. This applies to all additional properties owned by the investor, regardless of their main residence.
- Capital Gains Tax (CGT): When a buy-to-let property is sold for a profit, the investor is liable to pay capital gains tax on the difference between the purchase price and the selling price. The CGT rate for buy-to-let properties is 18% for basic rate taxpayers and 28% for higher rate taxpayers.
- Mortgage Interest Relief: Historically, landlords could deduct mortgage interest payments from their rental income to reduce their tax bill. However, this has been phased out and replaced by a 20% tax credit, which has reduced the overall tax efficiency of buy-to-let investments.
Risks and Challenges To Buy-to-Let Investments
While buy-to-let can be a lucrative investment, it also comes with risks and challenges that investors should consider:
- Property Market Fluctuations: Property values can rise and fall, and an economic downturn could result in negative equity, where the property is worth less than the outstanding mortgage.
- Vacancy Periods: There may be times when the property remains vacant, leaving the landlord without rental income but still responsible for covering costs such as the mortgage, insurance, and maintenance.
- Tenant Issues: Dealing with tenants can be challenging, especially if they fail to pay rent, damage the property, or require constant management. Additionally, planned changes to Section 21 evictions could make it increasingly challenging to remove
- Cash Flow Issues: With the abolishment of rental property tax reliefs such as the mortgage deduction and Multiple Dwellings Relief strict regulations on fees, deductions it can be challenging to operate rentals profitably.
- Compliance Issues: Another issue andlords face is staying on top of the constantly changing regulations and the introduction of new laws and requirements such as Minimum Energy Efficiency Standards and EPC requirements, Right to Rent Checks, HMO management, and the upcoming introduction of MTD for landlords.
Buy-To-Let Investing: Conclusion
Buy-to-let remains a popular investment strategy in the UK, providing investors with the opportunity to generate both rental income and capital growth. However, it is essential for potential landlords to be aware of the financial commitments, regulatory requirements, and risks involved. With the right approach, buy-to-let can be a profitable way to build long-term wealth.
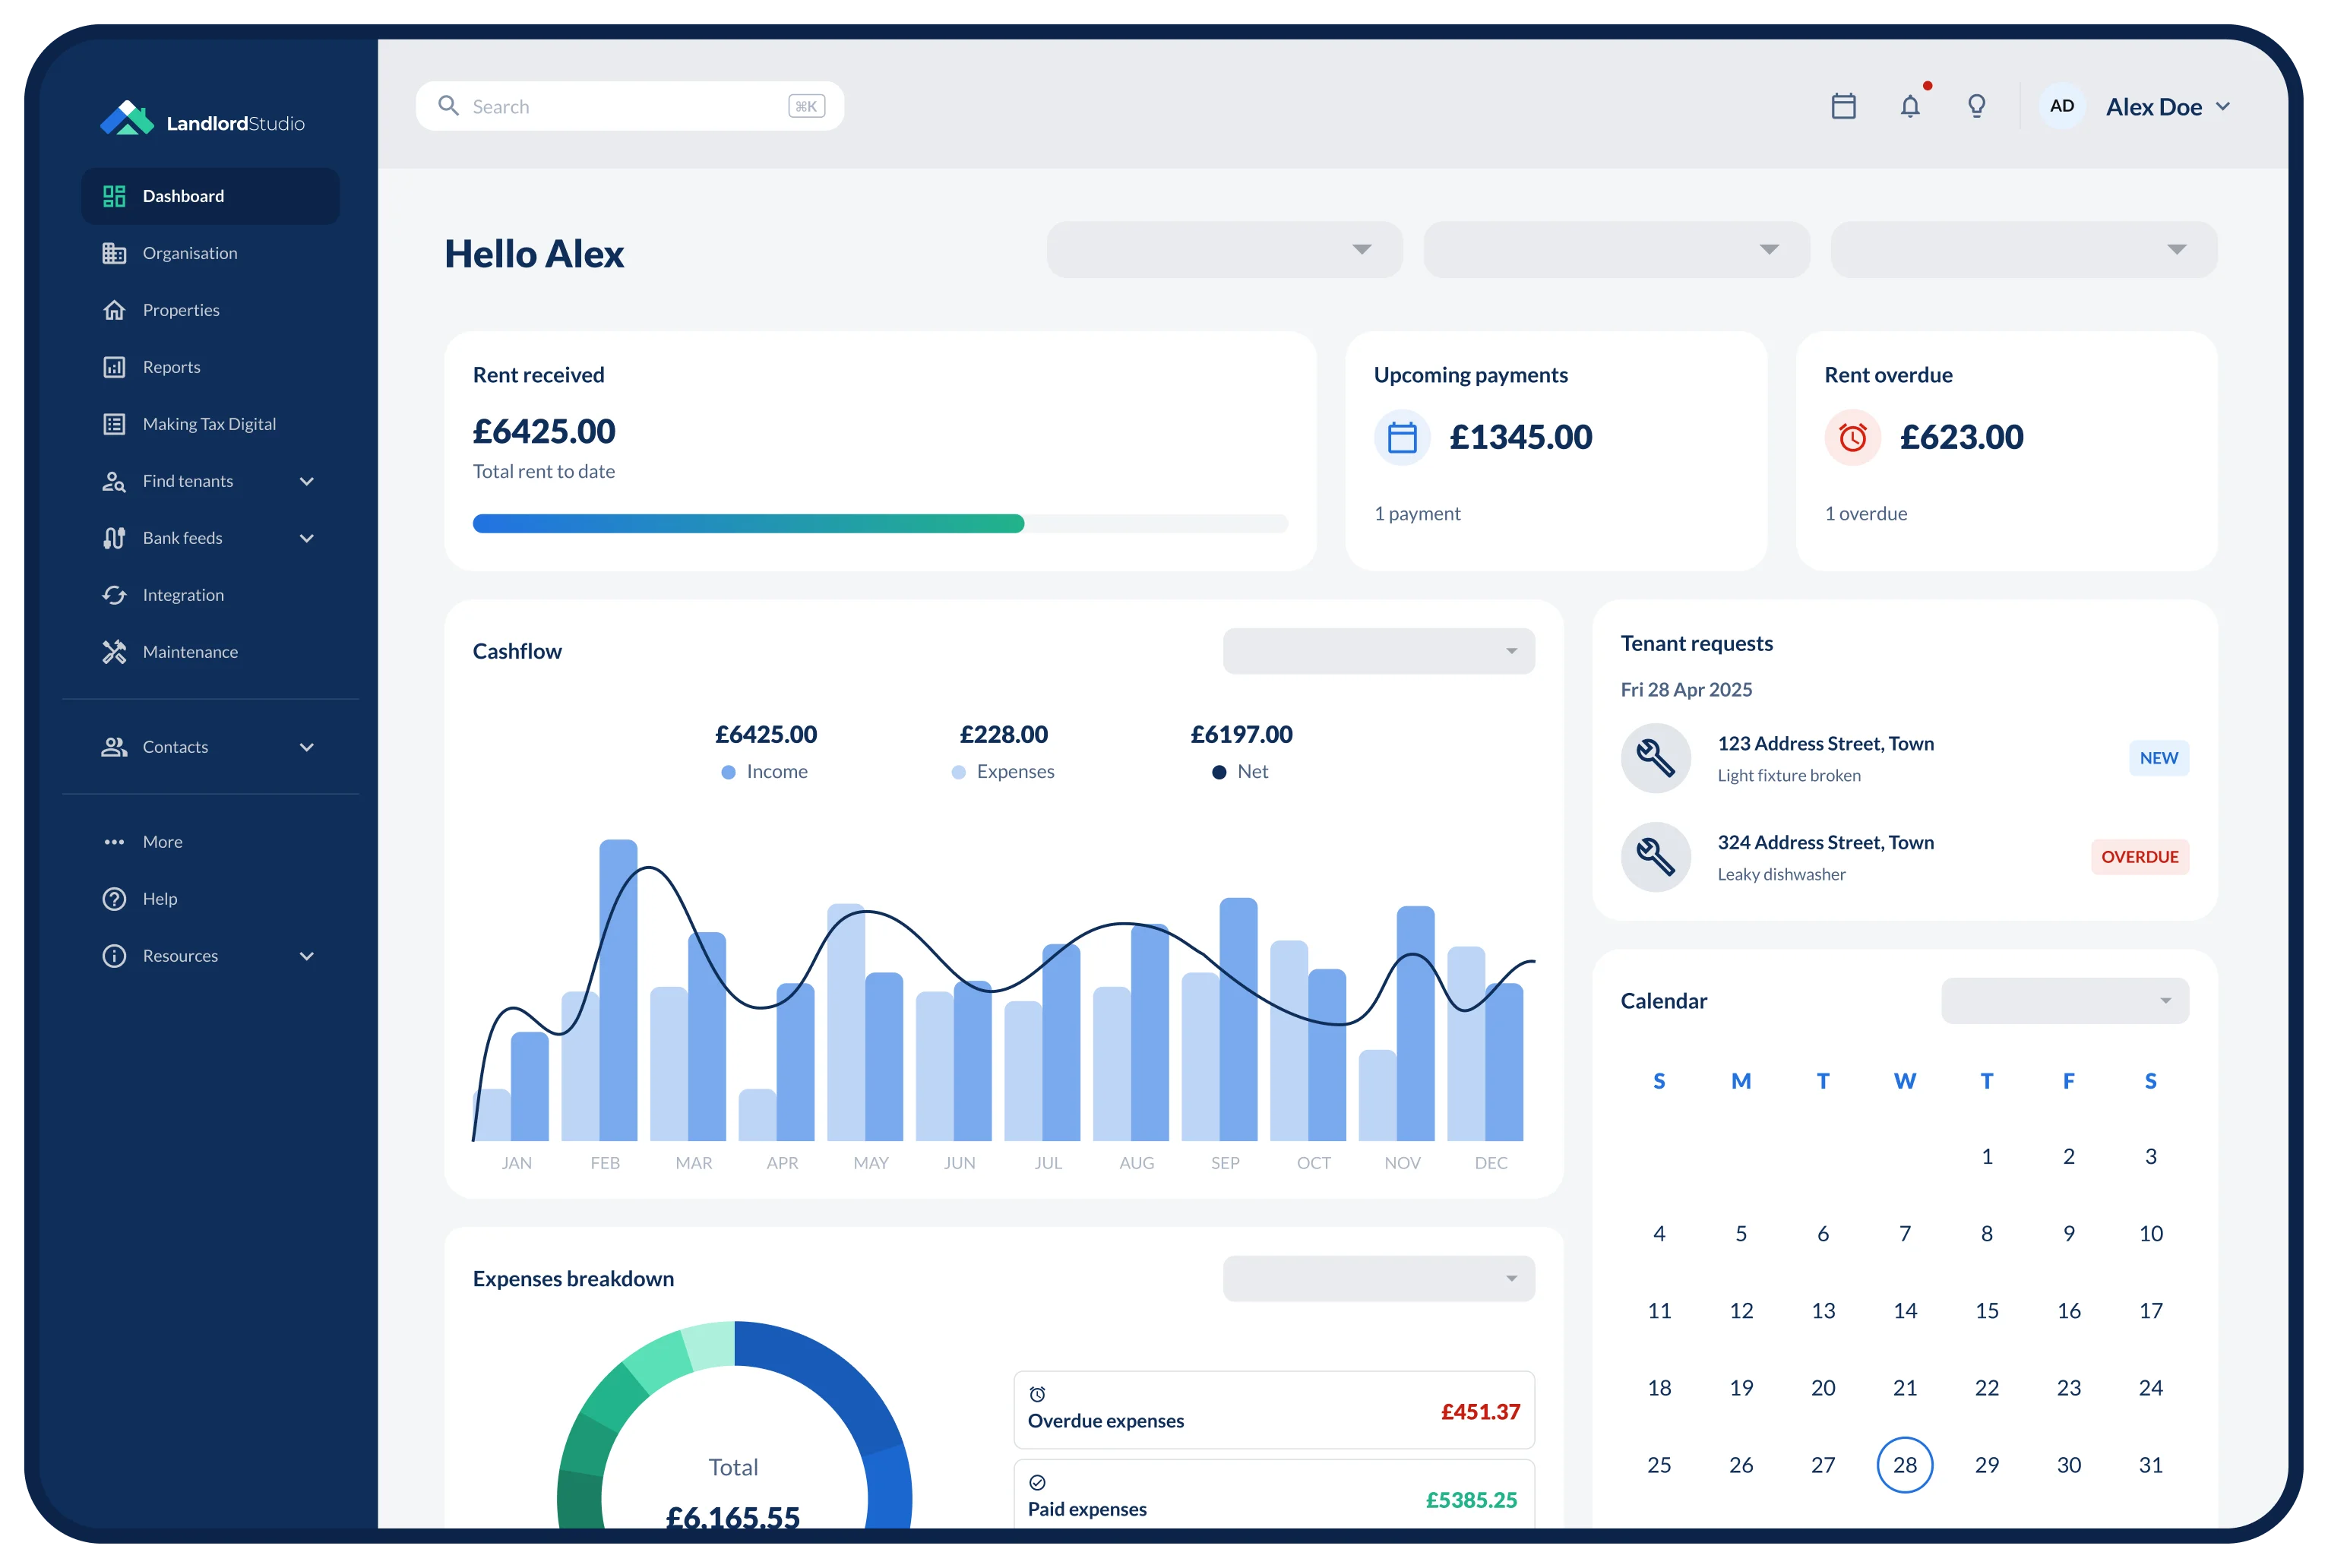
One way to stay on top of your buy-to-let properties is to employ property management software like Landlord Studio that is specifically designed for rental property management.
Landlord Studio provides UK landlords with a comprehensive set of features to help landlords efficiently manage their buy-to-let properties. Including rental accounting and financial reporting tools, reminders, document storage, maintenance tracking, and listings.
Stay on top of compliance issues and get ahead of MTD with digital record-keeping tool designed for you.